By Jason Johnson, REALTOR®, Jason & Stacey Johnson Realty | Keller Williams Lake Norman | October 8, 2026
This is my opinion, backed by the numbers. I am a REALTOR®, not a loan officer or an economist. Below is what I see in the data and why. Every figure is sourced at the end so you can check it yourself.
I get asked the same question almost every week. When are rates going back to 3%?
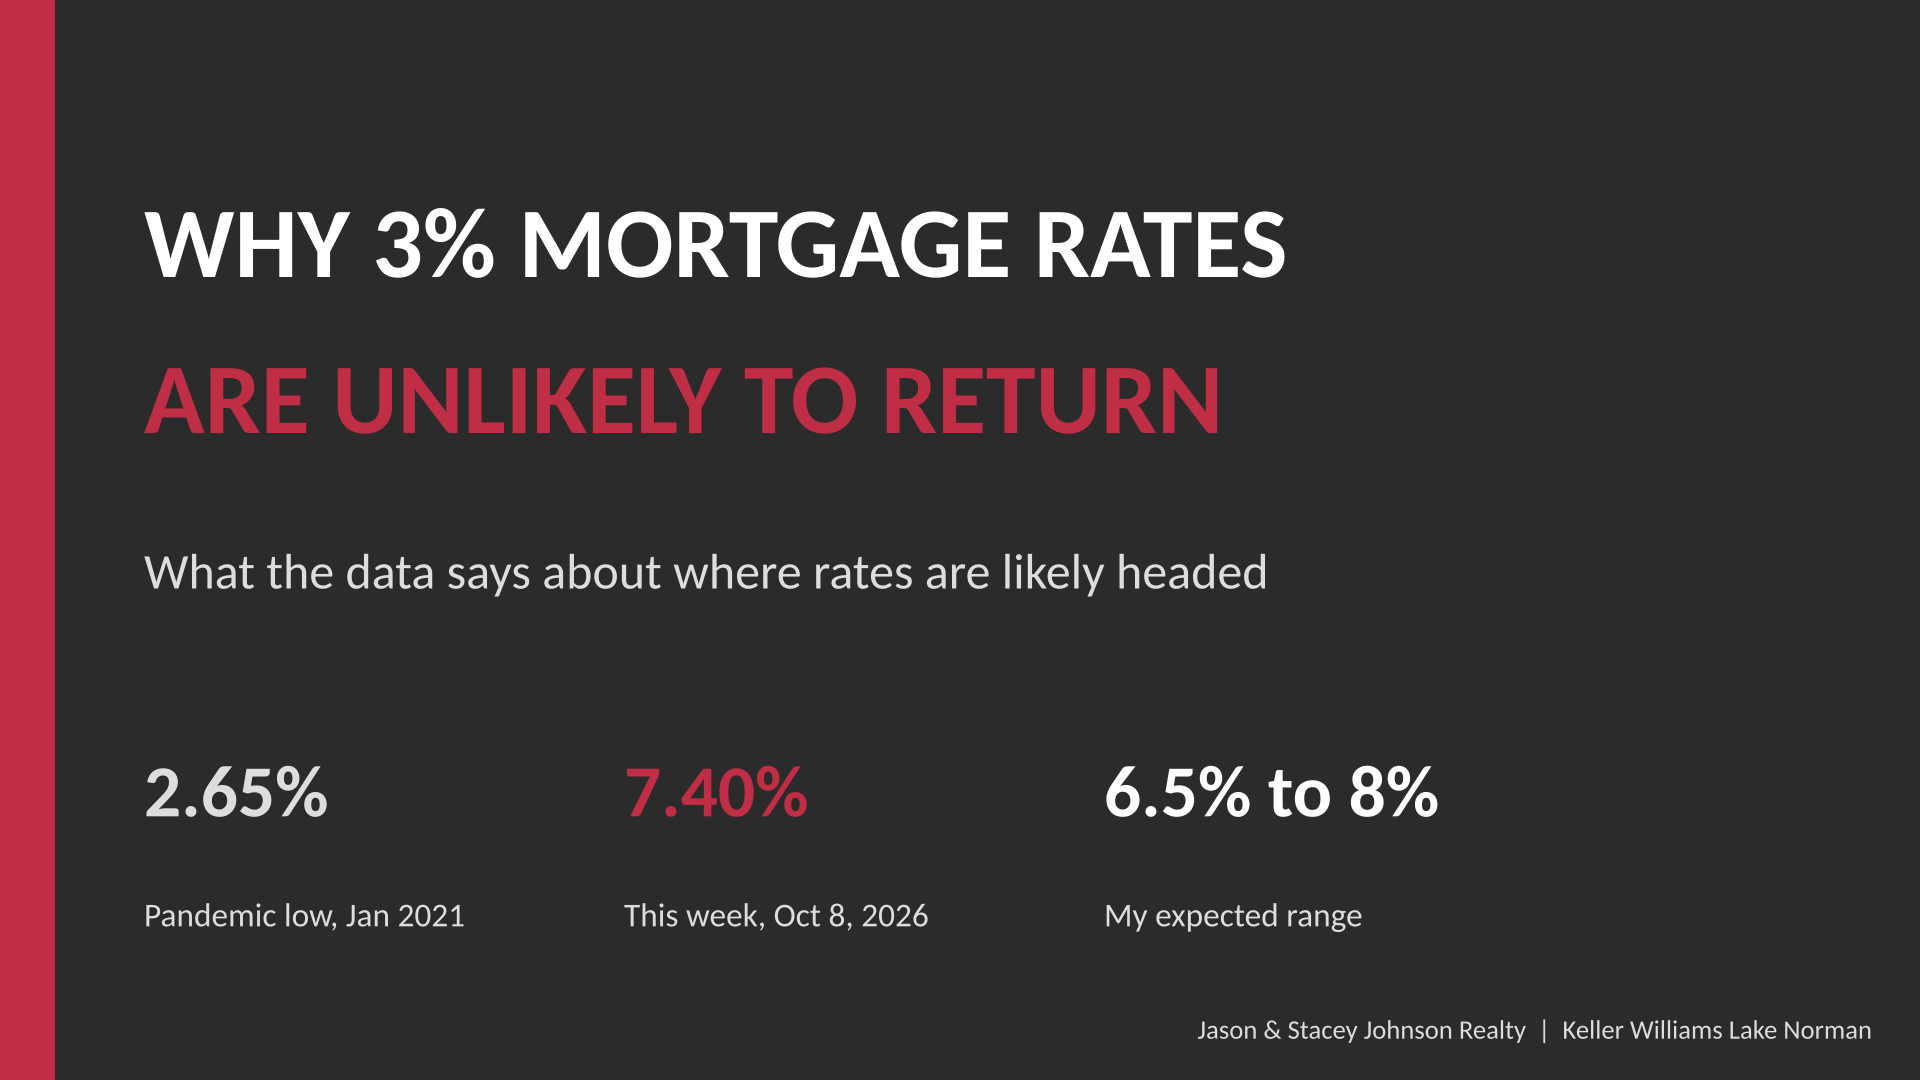
My honest answer is that I don't think they are. Not anytime soon. Based on what I am seeing in the data, I think a 30-year fixed rate somewhere between 6.5% and 8% is the more realistic picture for the foreseeable future.
The Short Answer: Will Mortgage Rates Go Back to 3%?
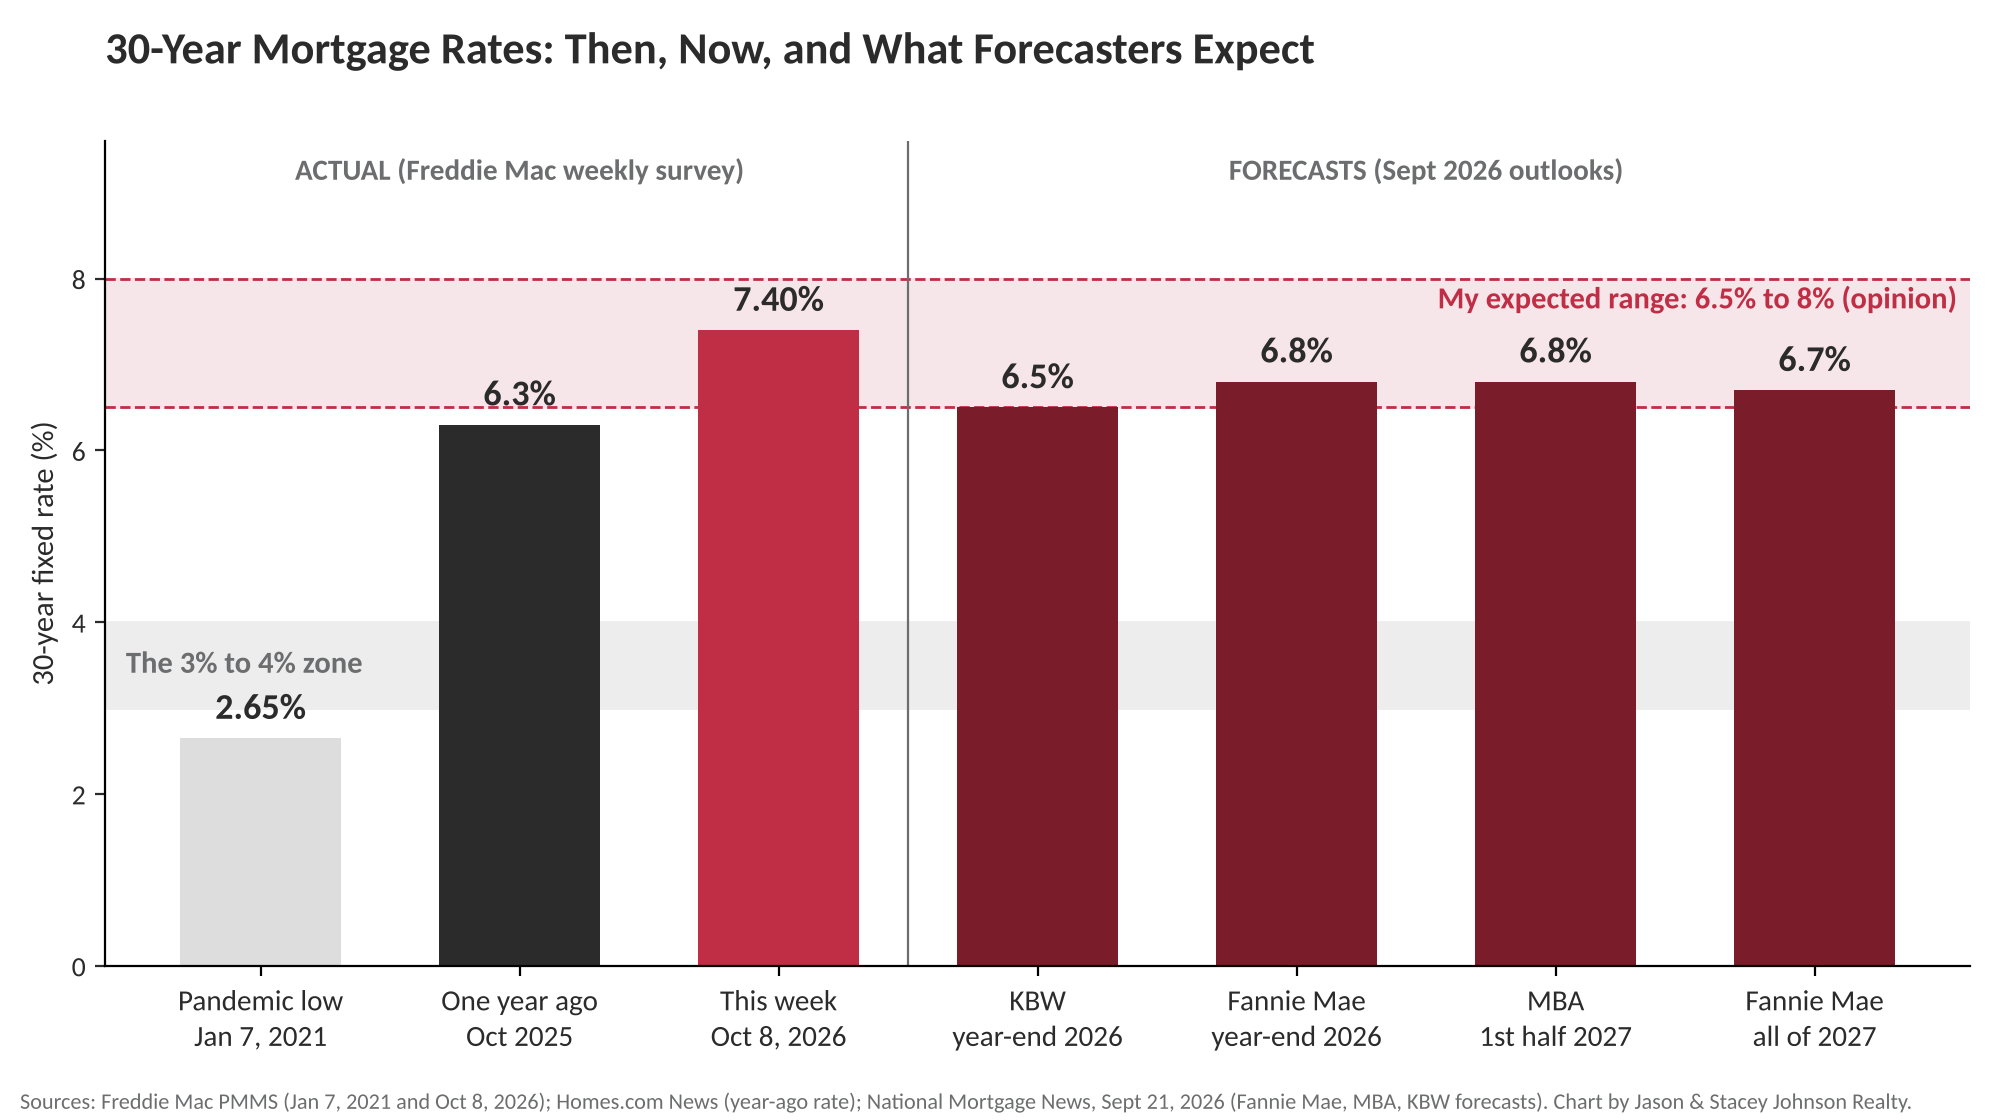
- Today. The 30-year fixed mortgage rate averaged 7.40% the week of October 8, 2026, per Freddie Mac. That is the highest since November 2023.
- The low. The pandemic low was 2.65% on January 7, 2021.
- The forecasts. Fannie Mae, the Mortgage Bankers Association, and KBW all forecast 6.5% to 6.8% for the end of 2026, not 3% or 4%.
- My view. Plan around 6.5% to 8%. That range is my opinion, not a forecast or a guarantee.
- The payment gap. On a $350,000 loan, 7.4% costs about $948 a month more in principal and interest than 3%.
Here is why.
Where Are Mortgage Rates Today?
The 30-year fixed rate averaged 7.40% this week, according to Freddie Mac's weekly survey. That is the highest level since November 2023. A year ago it was 6.3%. (Freddie Mac, Homes.com News)
Daily trackers ran even higher. Mortgage News Daily had the 30-year at roughly 7.5% to 7.6% on Thursday, depending on the time of day. (Real Estate News, Homes.com News)
Buyers are feeling it. The Mortgage Bankers Association (MBA) reported purchase applications down 15% from a year ago and refinance applications down 56%. (Real Estate News)
Why Are 3% to 4% Mortgage Rates Unlikely to Return?
For context, the lowest weekly rate during the pandemic was 2.65% on January 7, 2021. (Freddie Mac) In my view, rates like that came out of an emergency economy. They were not a normal market.
The forces pushing rates up right now have not gone away. Joel Berner, senior economist at Realtor.com, pointed to inflation expectations, a broad bond market selloff, and rising government debt. (Real Estate News)
The Federal Reserve also raised its short-term rate on September 16, and the 10-year Treasury yield was sitting around 5% in mid-September. (National Mortgage News) Mortgage rates tend to move with long-term bond yields like the 10-year Treasury, not just the Fed's rate.
Even the optimistic scenarios do not get anywhere near 3%. Redfin modeled how long it would take housing costs to get back to "normal." Its best case needs rates to fall to 6% and home price growth to go flat, a scenario Redfin itself called "unlikely." Redfin also noted its analysis is theoretical, not a prediction. (Real Estate News)
Notice that the best case is 6%. Not 3%. Not 4%.
What Do Forecasters Expect for Mortgage Rates in 2026 and 2027?
The bottom of my 6.5% to 8% range comes from the forecasters. In their September 2026 outlooks:
- Fannie Mae. Expects the 30-year to finish 2026 around 6.8% and average 6.7% for all of 2027.
- Mortgage Bankers Association. Also calls for 6.8% by the end of 2026, holding at 6.8% through the first half of 2027.
- Keefe, Bruyette & Woods (KBW). The lowest of the group, at 6.5% by the end of 2026.
(National Mortgage News)
Those forecasts were made in mid-September. Rates have climbed past them since. BTIG analyst Douglas Harter noted that rates were already pricing above 7%, higher than Fannie Mae called for, and said that adds downside risk to the forecasts. Doug Duncan, former chief economist at both Fannie Mae and the MBA, said that if the Fed keeps tightening, "it's not anytime soon that we're likely to see mortgage rates come down." (National Mortgage News)
The top of my range is my own cushion. None of the forecasts I cited calls for 8%. But we are already at 7.40% on the weekly survey, and daily rates have run higher. I would rather plan for some volatility than be surprised by it.
To be fair, not everyone expects rates to stay this high. One lender interviewed by Homes.com News expects a big reversal once the war in Iran ends and oil prices come down. He may be right. But even a full one-point drop from 7.40% still lands in the 6s. Another lender summed up the forecasting problem plainly: "All of our crystal balls were broken in February." (Homes.com News)
Nobody knows for sure. That includes me.
How Much Does the Mortgage Rate Change a Monthly Payment?
Here is what the rate does to a real payment. Same $350,000 loan, 30-year fixed, principal and interest only.
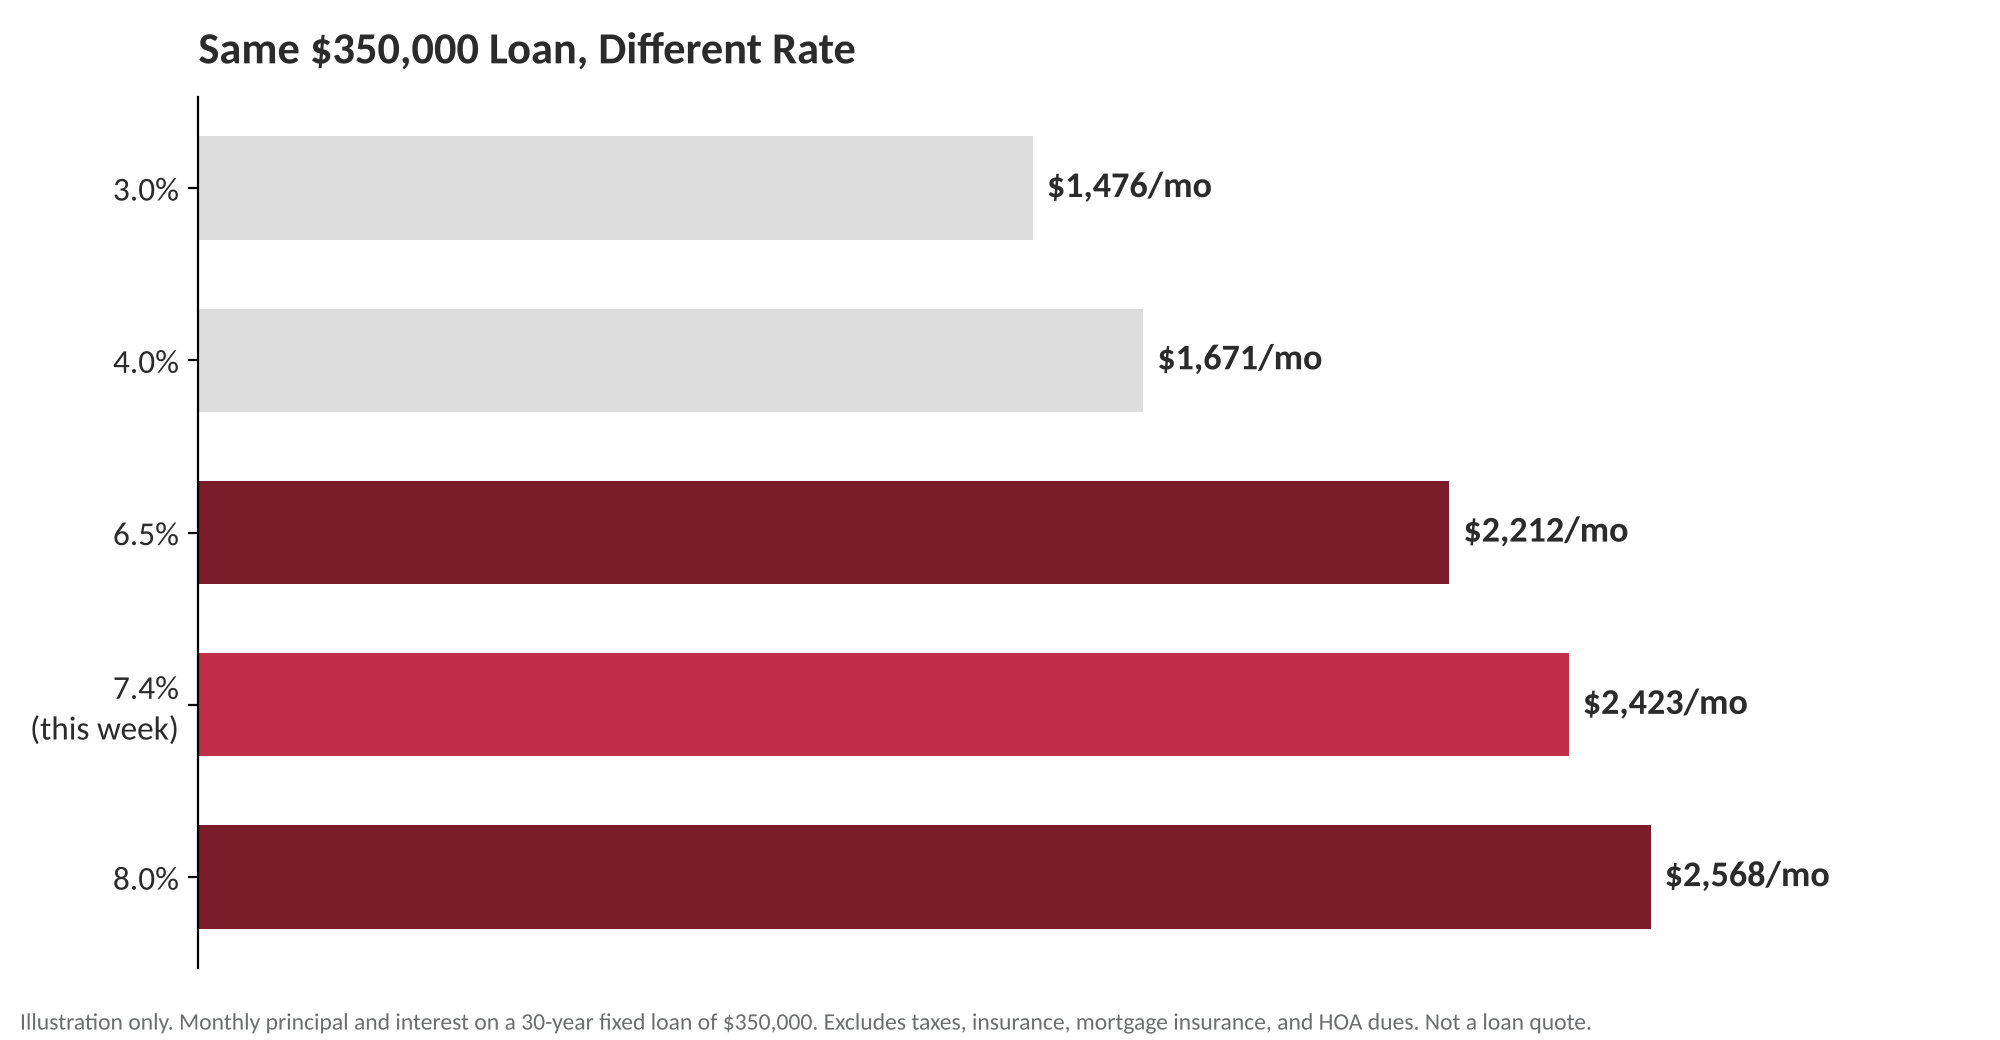
At 7.4%, that payment is about $948 a month more than at 3%. That is roughly $11,400 a year.
If you are waiting for that 3% payment to come back, you could be waiting a long time.
What Do Today's Mortgage Rates Mean for Buyers and Sellers?
If you are buying
Plan around the payment you can live with at today's rates, not the rate you hope for. Redfin senior economist Asad Khan put it well. Move when it makes sense for your finances and your life. If you need more time to save, take it. If you can afford it and you find the right home, don't let today's rates alone stop you. (Real Estate News)
Talk with a licensed loan officer about your options. Some builders are offering rate buydowns, and research from John Burns Research & Consulting found new homes are now about 2% cheaper than existing homes. (Real Estate News) A loan officer can tell you what actually fits your situation. I can't, and I won't pretend to.
If you are selling
Today's buyers are payment-driven. Pending sales have slowed and inventory is rising as homes sit on the market longer. (Real Estate News) That makes pricing and preparation more important, not less.
A home priced for the buyers who actually exist at 7% rates will get attention. A home priced like it is still 2021 will sit.
Some sellers decide to wait for rates to drop and buyers to come back. That can work. But waiting is not free. Every month you hold, you keep paying the mortgage, taxes, insurance, and upkeep. If rates stay in the range I expect, that wait could be a long one.
So run the numbers before you decide. We built a free Cost of Holding calculator for exactly this. Plug in your own numbers and it shows what holding your home costs over one, two, and three years, what you would net if you sold today, and the price you would need later just to break even. It also shows a range of price scenarios, from a 10% decline to a 10% increase per year. Those scenarios are illustrations, not predictions.
Try the Cost of Holding Calculator
Or type this address into your browser: https://jasonjohnsonrealty7-rgb.github.io/cost-of-holding/
Stacey and I build every pricing plan off current data, not hope. But it is ultimately your call.
Frequently Asked Questions About Mortgage Rates
What is the 30-year mortgage rate right now?
Freddie Mac's weekly survey put the average 30-year fixed rate at 7.40% for the week of October 8, 2026, the highest since November 2023. Daily trackers such as Mortgage News Daily ran higher, around 7.5% to 7.6%.
Will mortgage rates go back to 3%?
No major forecast I found calls for it. Fannie Mae, the MBA, and KBW project 6.5% to 6.8% by the end of 2026, and Redfin's best-case scenario only gets rates to 6%. My opinion is that 6.5% to 8% is the realistic range to plan around.
What do forecasters expect for mortgage rates in 2027?
As of their September 2026 outlooks, Fannie Mae expects the 30-year to average 6.7% for 2027, and the MBA expects 6.8% through the first half of 2027. Rates have since risen above those forecasts, and forecasts are not guarantees.
How much more is a mortgage payment at 7.4% than at 3%?
On a $350,000, 30-year fixed loan, principal and interest is about $1,476 a month at 3% and about $2,423 at 7.4%. That is roughly $948 a month, or about $11,400 a year. Taxes, insurance, mortgage insurance, and HOA dues are extra.
Should I wait for lower rates to buy or sell a home?
That depends on your finances and your plans. Waiting has real costs for sellers, including mortgage, taxes, insurance, and upkeep every month. Buyers should plan around a payment they can live with at today's rates and talk with a licensed loan officer about their options.
Bottom Line
I don't expect 3% or 4% rates to come back in the foreseeable future. Based on today's rates and the major forecasts, I think 6.5% to 8% is the realistic range to plan around.
I could be wrong. If rates surprise us to the downside, that is good news for everyone. But I would rather you plan with real numbers.
If you are buying or selling in the Lake Norman area and want to talk through what today's rates mean for your move, call or text me at 402-619-7492. You can also find more resources at www.LKNRealEstatePros.Com.
Jason Johnson
REALTOR® | Keller Williams Lake Norman
Jason & Stacey Johnson Realty
Cell: 402-619-7492
Email: [email protected]
www.LKNRealEstatePros.Com
Sources
- Dave Gallagher, "In best-case scenario, 'normal' housing market still 2+ years out," Real Estate News, October 8, 2026.
https://www.realestatenews.com/2026/10/08/in-best-case-scenario-normal-housing-market-still-2-years-out - Brad Finkelstein, "Fannie, MBA cut 2026 forecasts; plan for 6.8% rates," National Mortgage News, September 21, 2026.
https://www.nationalmortgagenews.com/news/fannie-mba-cut-2026-forecasts-plan-for-6-8-rates - Moira Ritter, "Mortgage rates climb to another three-year high," Homes.com News, October 8, 2026.
https://www.homes.com/news/mortgage-rates-climb-to-another-three-year-high/1064841964/ - Freddie Mac, Primary Mortgage Market Survey (PMMS), weekly data for January 7, 2021 and October 8, 2026.
https://www.freddiemac.com/pmms/pmms_archives
All graphics in this post were created by Jason & Stacey Johnson Realty from the sourced data above. Payment figures are standard 30-year amortization math.
Disclosure. This article reflects my personal opinion as a licensed North Carolina real estate broker, supported by the published sources listed above. It is general information, not financial, lending, investment, or legal advice. I am not a licensed mortgage loan originator. Mortgage rate forecasts are estimates by third parties and are not guarantees of future rates. Payment examples are illustrations only and are not loan quotes. Please consult a licensed mortgage professional about your specific situation. Services are provided without discrimination and with no requirement to use any affiliated vendor. The broker receives no compensation or referral fee from any lender or vendor mentioned. Each Keller Williams office is independently owned and operated. Jason Johnson, REALTOR®, NC License #362854.
Check out this article next